Sceptic-PK
Illuminator
- Joined
- Jun 22, 2010
- Messages
- 3,831
I thought you said banks don't lend out deposits?


Perhaps you should read it and provide excerpts you think support your position, because fractional reserve banking just doesn't work the way you think it does. Banks cannot and do not loan out "invented" money.
The actual process of money creation takes place
primarily in banks.' As noted earlier, checkable liabilities
of banks are money. These liabilities are customers' accounts.
They increase when customers deposit currency
and checks and when the proceeds of loans made by the
banks are credited to borrowers' accounts.
In the absence of legal reserve requirements, banks
can build up deposits by increasing loans and investments
so long as they keep enough currency on hand to redeem
whatever amounts the holders of deposits want to convert
into currency. This unique attribute of the banking business
was discovered many centuries ago.
It started with goldsmiths. As early bankers, they
initially provided safekeeping services, making a profit from
vault storage fees for gold and coins deposited with them.
People would redeem their "deposit receipts" whenever
they needed gold or coins to purchase something, and
physically take the gold or coins to the seller who, in turn,
would deposit them for safekeeping, often with the same
banker. Everyone soon found that it was a lot easier simply
to use the deposit receipts directly as a means of payment.
These receipts, which became known as notes, were acceptable
as money since whoever held them could go to
the banker and exchange them for metallic money.
Then, bankers discovered that they could make loans
merely by giving their promises to pay, or bank notes, to
borrowers. In this way, banks began to create money.
More notes could be issued than the gold and coin on hand
because only a portion of the notes outstanding would be
presented for payment at any one time.
We're talking about fractional lending
Which I might add, despite a few fairly serious issues in its infancy, has been a resounding success compared to the panics of the 19th Century.
As already pointed out, I read it years ago...
There is nothing that prevents a bank from lending out deposits.
You can read all about it in MMM under "Deposit Expansion", sections 3-10.
Still waiting for you to reconcile...
banking collapses have occurred several times over the last 100 years. I thought they could just invent more money, right?
Ah, fractional reserve banking, as sanctioned by...oh, that's right, the Federal Reserve issues those rules. So it's splitting hairs to suggest we're not talking about the Federal Reserve.
Then you must surely know what I say about it is correct.
I don't know if that's legal or not, but I know all banks do otherwise. They don't loan out any money, they get a promise to pay back a loan, and in exchange they give the promiser "credits" on their account that they create with ledger entry as a "liability". The banks are able to loan out many times what's been deposited, in actuality.
Every bank routinely carries "liabilities" in excess of ten times their reported deposits. They don't dip out of your savings account to make a business loan to your boss.
The text you cite accords with the description of banks merely "inventing" money,
but as stated before, they don't invent money to cover the extra debt of "interest", they just invent the principal, so there is never money in the supply to pay back the interest. There's no way around that fact, it's how the system is designed.
Still waiting for you to apologize for calling me a clown. Consider this response a courtesy, no thanks are necessary.
As I've explained, the game relies on a rapidly expanding (exponential) money supply. Clearly in a physical world this is unsustainable.
Every so often they have to rest it all, before the system runs itself into the ground and people carry wheelbarrows of money to buy a loaf of bread.
Well, psionl0 seems to be asserting that FRB has existed for hundreds of years, so maybe you two can resolve that quandry together. No, you are incorrect in almost everything. It is sophistry of the highest order. It's no better than all the other nonsense posted in this thread before you got here. And what limits the lending champ? The amount of deposits or assets of the bank. Go read MMM again, sections 3-10 under expansion like I suggested.
What is a "liability" then, if, according to you, the banks don't care if someone pays them back or not? Not much of a liability huh?
I already addressed this claim several pages ago. In the US, with a reserve requirement of 10%, it is impossible for a bank to lend out 10x its reserves.
They don't invent it, it is created as a liability on their balance sheet against their reserves. If nobody pays that money back, it becomes very real to the bank.
Repeating incorrect claims ad nauseum will not suddenly make them right.
You're obsessed with money creation via commercial banks, and ignore all the money created by the government. Repeat after me: not all money created is based on debt!
Right. When was the last time the US suffered hyperinflation again?
What I am arguing about is the assertion that the money is created from nothing, rather than being based upon the reserves of the bank in question...
Mann's curious opinion that banks can create as much money as they want, and liabilities don't really exist.
My quote from MMM above should demonstrate that fractional reserve banking is a lot more than 100 years old.I'm still waiting for your history lesson of FRB over the last several hundred years.
What I am arguing about is the assertion that the money is created from nothing, rather than being based upon the reserves of the bank in question, and Mann's curious opinion that banks can create as much money as they want, and liabilities don't really exist.

The source material for these claims? Modern Money Mechanics, page 6.
From page 3 of MMM: (red highlights mine)
As noted earlier, checkable liabilities of banks are money. These liabilities are customers' accounts. They increase when customers deposit currency
What are you arguing about Sceptic-PK? The borrower signs a loan agreement and the bank credits the borrower's account with the agreed amount. Money created. End of story.
The percentage varies but let's say it's ten percent. That means for every "real" dollar in a bank, that bank can invent ten dollars to loan out, citing demand for the loan as their authority to invent it.
You highlighted the wrong part, here is the key section:As noted earlier, checkable liabilities of banks are money. These liabilities are customers' accounts. They increase when customers deposit currency and checks and when the proceeds of loans made by the banks are credited to borrowers' accounts.
Yes, bookkeeping 101. The customer's LOAN account is debited and the customer's DEPOSIT account is credited by the same amount.Under double entry book keeping when the bank credits your account they have have record a corresponding debit someplace else.
Wrong again. For every dollar a bank possessed, it may lend 90c. You can't get even the simple things right. I will not waste another minute on your nonsense.
Actually, I couldn't find anything like that on page 6. What I did find was the following:yeah, that doesn't say what you claimed. It says people don't normally make deposits in the form of cash, so the bank takes promissory notes, AKA checks.The source material for these claims? Modern Money Mechanics, page 6.
you have anything else?
Perhaps you should read it and provide excerpts you think support your position, because fractional reserve banking just doesn't work the way you think it does. Banks cannot and do not loan out "invented" money.
yeah, that doesn't say what you claimed.
Wrong again. For every dollar a bank possessed, it may lend 90c.
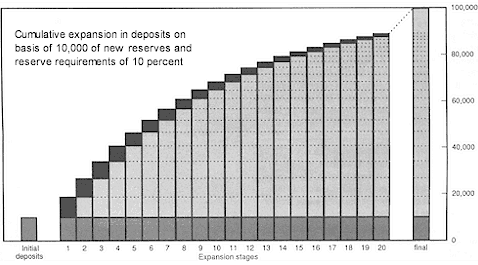
The total amount of expansion that can take place is illustrated on page 11. Carried through to theoretical limits, the initial $10,000 of reserves distributed within the banking system gives rise to an expansion of $90,000 in bank credit (loans and investments) and supports a total of $100,000 in new deposits under a 10 percent reserve requirement. The deposit expansion factor for a given amount of new reserves is thus the reciprocal of the required reserve percentage (1/.10 = 10). Loan expansion will be less by the amount of the initial injection. The multiple expansion is possible because the banks as a group are like one large bank in which checks drawn against borrowers' deposits result in credits to accounts of other depositors, with no net change in the total reserves.